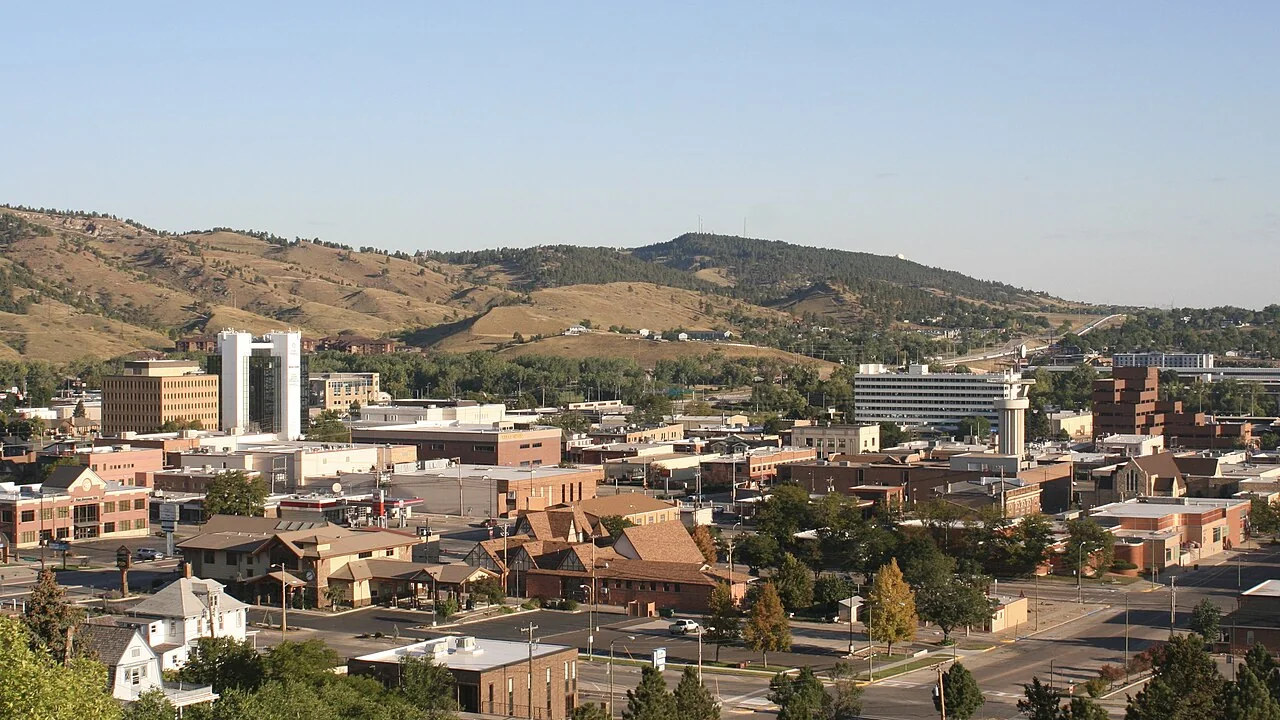

Rapid City is a place where a wooded ridge can remain part of an urban neighborhood rather than a distant wilderness setting. A house near Skyline Drive, a home toward the western Black Hills edge and a property on more open ground should not be described as the same insurance risk. The details immediately around the building are essential.
Skyline is an urban landscape reference, not a rating
Rapid City's official materials identify Skyline Drive and Dinosaur Park as familiar elevated locations within the city. Pennington County's historical hazard planning also includes wildfire imagery associated with Rapid City. These sources show why citywide preparation cannot be limited to remote cabins. They do not provide a current risk classification for every house along a named ridge.
For a residence in that setting, identify what lies below the rear elevation and who owns it. Show the relationship between trees, slope, deck and neighboring structures. A downtown panorama may establish the location beautifully, but it cannot demonstrate that needles have been removed from the roof or that materials beneath a deck have been cleared.
Black Hills history belongs in perspective
The Forest Service's regional fire-history mapping records Westberry Trails in 1988 near Rapid City. That is a historical landscape reference, not an active incident or a prediction of a repeat path. Use the record to understand why local preparation is established work rather than a new concern created solely by an insurance letter.
For your own house, ask what has changed since it was built or last assessed. A new deck, altered landscaping, added guest space or neighboring development can change the information an agent needs. Current photographs and construction records should accompany historical context. An old map cannot show the materials and maintenance at today's residence.
Verify which local agency serves the parcel
Rapid City Fire and Pennington County Fire Administration have different responsibilities, and the county supports fire departments across a much larger area. Confirm the agency serving the property before supplying details about protection or access. The mailing address is not a substitute for that check, especially for a home outside municipal boundaries.
Ask the appropriate office where to obtain a home assessment and how to describe water supply or driveway access accurately. Avoid guessing at response times, hydrant distances or service arrangements. If a private gate, shared road or narrow approach needs attention, document it and seek qualified guidance. Those facts may also help the household plan before an emergency interrupts ordinary travel.

Ask South Dakota Wildland Fire about mitigation support
South Dakota's wildland-fire program publishes information on property assessments and hazardous-fuels cost sharing. Its purpose includes improving conditions around homes and addressing hazardous vegetation. Contact the program for current eligibility and project requirements before hiring a contractor on the assumption that a particular share of the work will be reimbursed.
For a wooded Rapid City-area lot, an assessment can help set priorities without treating every tree as a problem. Ask which tasks require professional skill, what should remain and how debris will be handled. If the recommended work extends beyond your boundary, identify the responsible owner. No grant, assessment or completed thinning project should be represented as a guaranteed insurance approval.
Look at the building-to-yard connections
On a sloping property, the underside of an elevated deck may require a separate photograph. In a more developed neighborhood, the relevant connection may be a fence, detached garage or line of stored household materials. Ask an assessor to explain the pathways on your parcel rather than copying a diagram without considering the actual layout.
Describe the whole property, including guest spaces
A house near the Black Hills may include a detached garage, workshop, accessory dwelling or space offered to guests. Explain each use before comparing insurance proposals. A building used for household storage creates different questions from one containing business equipment or paying occupants. Provide dimensions and construction details so the professional can identify where protection is needed.
Ask how the dwelling replacement estimate treats decks, additions and distinctive materials. Review the amount for other structures instead of assuming a default figure matches the parcel. The South Dakota Division of Insurance publishes homeowners guidance, but the licensed professional should explain the actual policy forms and limits offered for your residence.
Do not let one hazard obscure the rest of the policy
Wildfire may have prompted the search, yet the proposed contract also needs to fit other household needs. Ask about the dwelling, belongings, liability, deductibles and additional living expenses after a covered loss. If the home has had prior damage from another cause, provide the claim date and completed repair information accurately.
Discuss any water or earth-movement concerns separately, particularly where the property meets sloped ground. A broad label such as “full coverage” does not answer those questions. Ask the agent to identify relevant exclusions, endorsements and conditions in writing. The coverage-options guide can help structure a comparison, while the contract supplies the actual terms.
Turn a nonrenewal into a documented next step
Keep the written notice and clarify its effective date. Ask which concerns are specific to the residence and what documentation could support another review. Organize completed work separately from estimates or projects waiting for permission. If an inspection is required, find out when it occurs and how unfinished recommendations affect the proposal.
Our nonrenewal guide provides a practical document sequence. A licensed specialist may be able to explore alternatives, but confirm placement and effective dates before changing existing coverage. If an explanation is unclear, the state's Division of Insurance has consumer resources. Seeking clarification early is easier than trying to reconstruct conflicting messages at the deadline.
Make household readiness a separate routine
Pennington County Emergency Management provides preparedness and public-warning resources. Use those official channels for current conditions and instructions. Do not designate a Skyline recreation trail or a familiar forest road as an emergency exit based only on this article. Discuss communication, pets and help for household members who may need assistance leaving.
Keep an inventory and insurance documents accessible from another location. Update the property file after remodeling or major vegetation work. The useful result is a plan tied to a specific Rapid City home: verified service information, realistic maintenance and a coverage discussion that acknowledges the building's actual use. That gives each professional a clear question to answer and makes the overall process more manageable.
Explore the South Dakota guides
Read the South Dakota wildfire insurance overview for state resources and questions about available insurance paths.
Common questions
Does a Skyline Drive address mean insurers all make the same decision?
No. A landmark provides geographic context, not a universal underwriting result. Show the actual building, slope, access and completed work. Ask the agent what a particular company requires rather than assuming every house near the ridge receives the same classification or offer.
Can a Rapid City homeowner request help with vegetation work?
South Dakota Wildland Fire publishes assessment and fuels-mitigation assistance resources. Confirm current eligibility, funding and approval steps directly before committing to a project. The program’s objectives and an insurer’s conditions are separate, so discuss both when organizing the work.
Why verify the fire agency for a Rapid City mailing address?
The postal name does not establish municipal boundaries or service arrangements. Check the responsible agency and obtain accurate access and protection information. This helps direct assessment questions to the right office and avoids unsupported statements in an insurance application.
What records are useful after a deck or roof project?
Keep the invoice, material description and dated photographs showing the completed work. For a deck on sloped ground, include a safe wider view of the underside and surroundings. Mark estimates as pending so the agent can distinguish finished improvements from future plans.
Sources and further reading
- Rapid City: Fire Department
- Rapid City: Skyline Drive and Dinosaur Park local references
- Pennington County: Fire Administration
- Pennington County: Emergency Management
- USDA Forest Service: Black Hills historical fire map
- South Dakota Wildland Fire: fuels mitigation assistance
- South Dakota Division of Insurance: homeowners guidance
Program rules and insurance terms can change. Check the linked agency or program before relying on eligibility, coverage, or local requirements.
General educational information. This website does not issue policies, bind coverage, or provide emergency alerts. Coverage and eligibility require individual review.