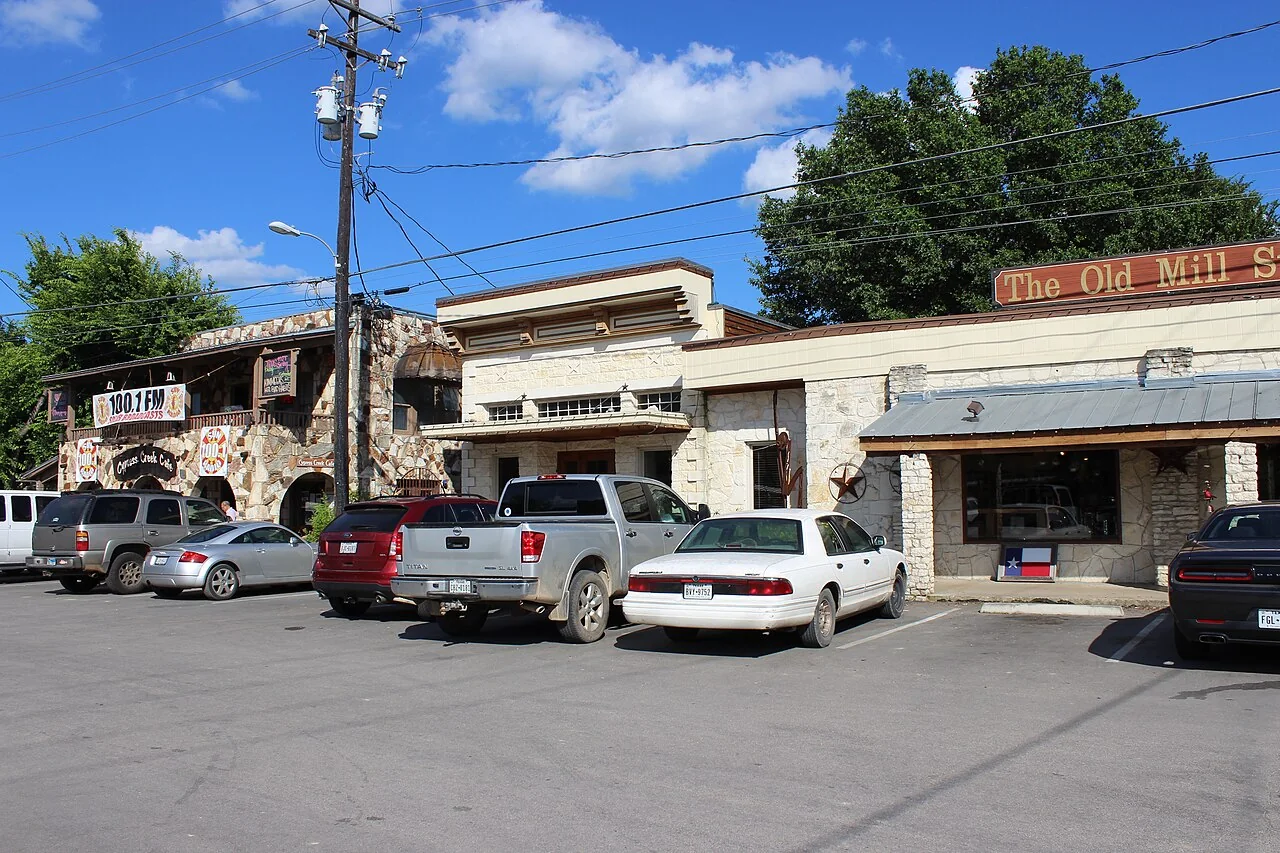

In Wimberley, a home can feel sheltered by trees while depending on a narrow driveway or a creek crossing for access. Another property may sit near the developed village with neighboring buildings close by. The same mailing address can cover very different arrangements, so a useful wildfire insurance discussion begins with the actual residence and the way people reach it.
Coverage trouble is stressful, especially when a renewal date is approaching. You can make progress by separating three questions: what the insurer is concerned about, what property information is available and which improvements or alternative markets deserve review. A specialist agent can work through those questions without reducing every Wimberley home to a generic Hill Country description.
Creek-country access belongs in the wildfire conversation
Wimberley's Blanco River and Cypress Creek setting is central to how residents move around the valley. A house can have a convenient daily route that is less straightforward during an emergency. For a property review, describe the driveway, bridges or crossings, gate access and any alternative connection that actually exists. Do not draw an emergency route simply because it looks short on a map.
Hays County Emergency Management includes Wimberley and Woodcreek in its planning responsibilities and describes a county flood-warning system. That local context makes an all-hazards approach sensible. Wildfire and flood are different hazards, but both can affect access. Ask officials how your household should receive instructions rather than assuming one familiar crossing will always be available.
A wooded retreat needs a close view of the structure
For a Wimberley house tucked among Hill Country vegetation, wide landscape pictures alone leave important questions unanswered. Show where shrubs approach windows, where a deck extends over ground cover and where leaves accumulate around an outdoor stair. Include the building's less visible side, which may differ substantially from the carefully maintained entrance.
Keep the property boundary in mind. A view of woodland across a fence does not mean that you can alter that vegetation. Shared access, neighboring acreage and conservation responsibilities can complicate a maintenance proposal. Ask for local guidance before significant clearing, and describe completed work accurately. Replacing an entire landscape is not the starting point for every useful mitigation improvement.
A professional can help you assess roof edges, vent protection, combustible storage and attachments before larger projects. Our defensible-space resource can help structure the discussion. Take before-and-after photographs when work is performed, but avoid calling the home fireproof or claiming that an improvement must result in insurance acceptance.
Wimberley Fire Rescue and the county have distinct roles
Wimberley Fire Rescue identifies itself with Hays County Emergency Services District No. 4. Its public resources include fire-safety education. Confirm that the department serves your particular address and ask where property-specific access or prevention questions should go. The name of the community and the name on a fire-service jurisdiction are related details, not interchangeable ones.
The Hays County Fire Marshal provides county fire-prevention information and references the Community Wildfire Protection Plan. Consult that office or the appropriate city authority for applicable requirements. County planning is useful background; it is not an insurance endorsement or a certificate that your building meets every condition an insurer might impose.

Describe guest cabins and rental use before requesting quotes
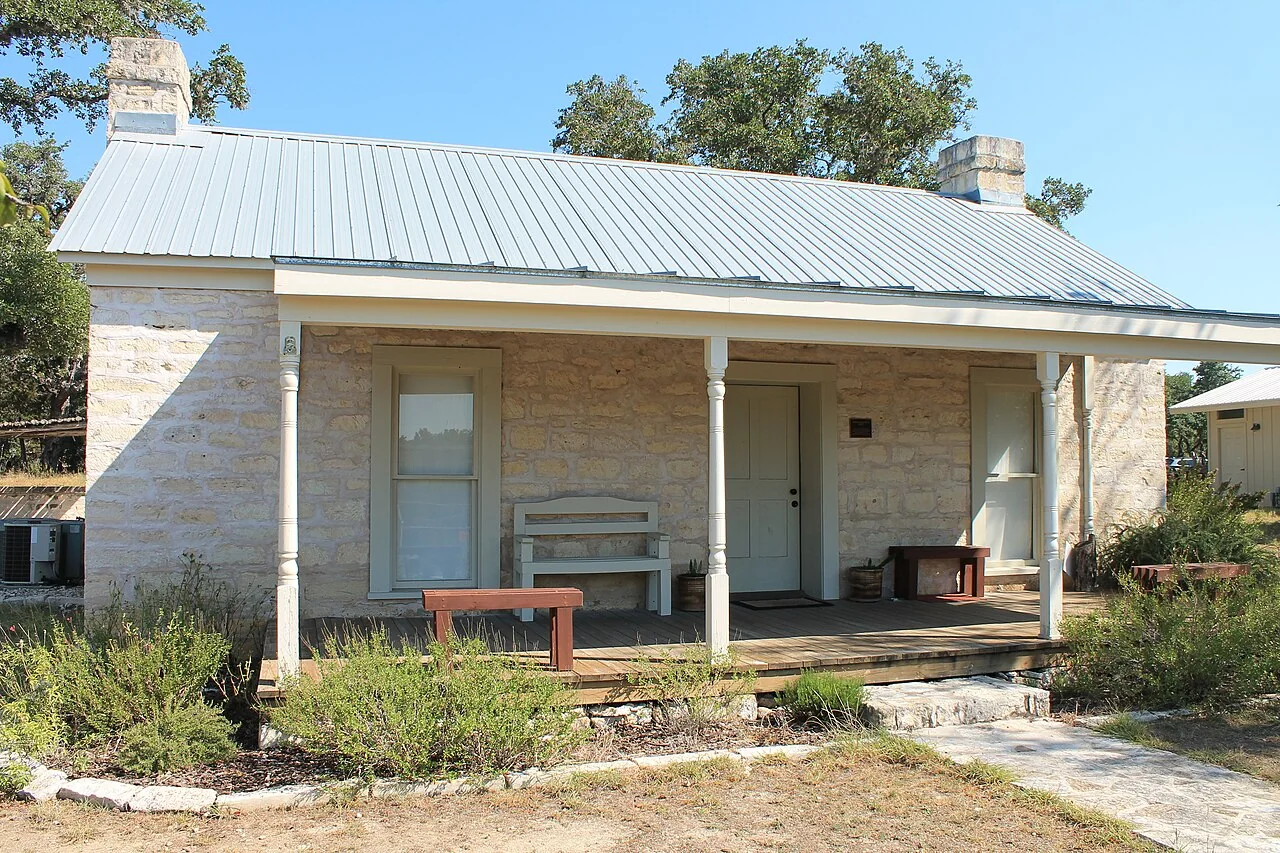
For any Wimberley property with a separate guest cabin, studio or detached dwelling, explain the occupancy in plain language. Is it reserved for family, offered for short stays, leased for longer periods or used for work? Include the number of buildings and their construction. The agent needs the actual arrangement, even if the property has always been described casually as a single home.
Ask which policy would address the dwelling, other structures, furnishings and relevant liability exposures. If rental income matters to your finances, discuss how interruption of that use would be treated. Do not assume a personal homeowners quotation accommodates every guest arrangement. A clear description early in the process is easier to resolve than a mismatch discovered after a loss.
Prepare a file that explains the home without exaggerating
Start with the existing declarations, any nonrenewal or inspection notice and the date coverage is scheduled to end. Add the roof age, year of construction, additions, exterior materials and known repairs. Where a detail is uncertain, label it for confirmation. A guessed roof age or an assumed hydrant distance can make an otherwise helpful submission less reliable.
For an elevated deck or hillside residence, show the underside and surrounding ground from a safe location. For a gate, explain the established emergency access arrangement through a secure channel. For a repaired claim, include the cause, date and completion evidence. Tell the agent what changed since the insurer's last inspection instead of relying on an undated claim that the property has been improved.
Compare policies against the cost of rebuilding your particular place
A Wimberley property's sale price may reflect land, views or location, while rebuilding involves a different calculation. Ask the agent how the estimate handles the building's size, finishes, foundations, access and detached structures. If a cabin has unusual materials or a main house has extensive outdoor living areas, ensure those details are included in the discussion.
Request explanations of fire deductibles, smoke-related damage, personal belongings, debris removal and temporary living arrangements after covered damage. Ask about the amount and duration of any relevant benefit. Keep flood insurance questions separate because being near a creek does not make wildfire coverage a substitute for flood protection. The actual contract determines the coverage, exclusions and conditions.
The Texas Department of Insurance guide is a useful place to review basic shopping questions. If placement is difficult, compare the options an appropriately licensed agent can identify, including any applicable surplus-lines or Texas FAIR Plan route. Ask how proposed coverage differs from your current policy instead of assuming a lower price means equivalent protection.
Build the household plan around the people who use the property
The City of Wimberley's emergency operations plan provides local planning context. A household or guest arrangement still needs its own practical preparation: who receives alerts, who can assist someone with limited mobility and where essential documents are kept. Visitors should know the property's address and whom to contact, not just a rental's marketing name.
Check current instructions through official local channels. Older fire-safety pages can display a past burn-ban date, so do not rely on a cached notice as permission for outdoor burning. During an actual incident, follow emergency directions immediately. Organizing insurance paperwork and property maintenance before that moment makes both tasks less overwhelming.
Explore the Texas guides
Read the Texas wildfire insurance overview for state resources and questions about available insurance paths.
Common questions
Why discuss creek crossings when the concern is wildfire?
A crossing is part of your access arrangement, and different emergencies can affect it. Record the actual route and ask local officials about planning. Do not assume a daily commute or a map shortcut is an approved evacuation route.
Who should review a Wimberley gate or driveway question?
Start by confirming the fire agency serving the address. Wimberley Fire Rescue provides a local contact point, while county or city authorities can address applicable requirements. Share security-sensitive access details through the channel the responsible agency recommends.
Does a detached guest cabin need to be mentioned?
Yes. Tell the agent how it is occupied and whether money changes hands. Ask about the structure, its contents and the liabilities of that use. A guest cabin cannot be assumed to have the same treatment under every homeowners contract.
Will a county wildfire plan make my home insurable?
A community plan supports local preparedness and mitigation decisions. It does not decide individual insurance eligibility. Combine that background with accurate construction details, maintenance evidence and the specific information requested by the insurer reviewing your Wimberley property.
Sources and further reading
- Hays County: Emergency Management
- Wimberley Fire Rescue
- Hays County Fire Marshal
- City of Wimberley: Emergency operations plan 2025
- TDI: Home insurance guide
Program rules and insurance terms can change. Check the linked agency or program before relying on eligibility, coverage, or local requirements.
General educational information. This website does not issue policies, bind coverage, or provide emergency alerts. Coverage and eligibility require individual review.