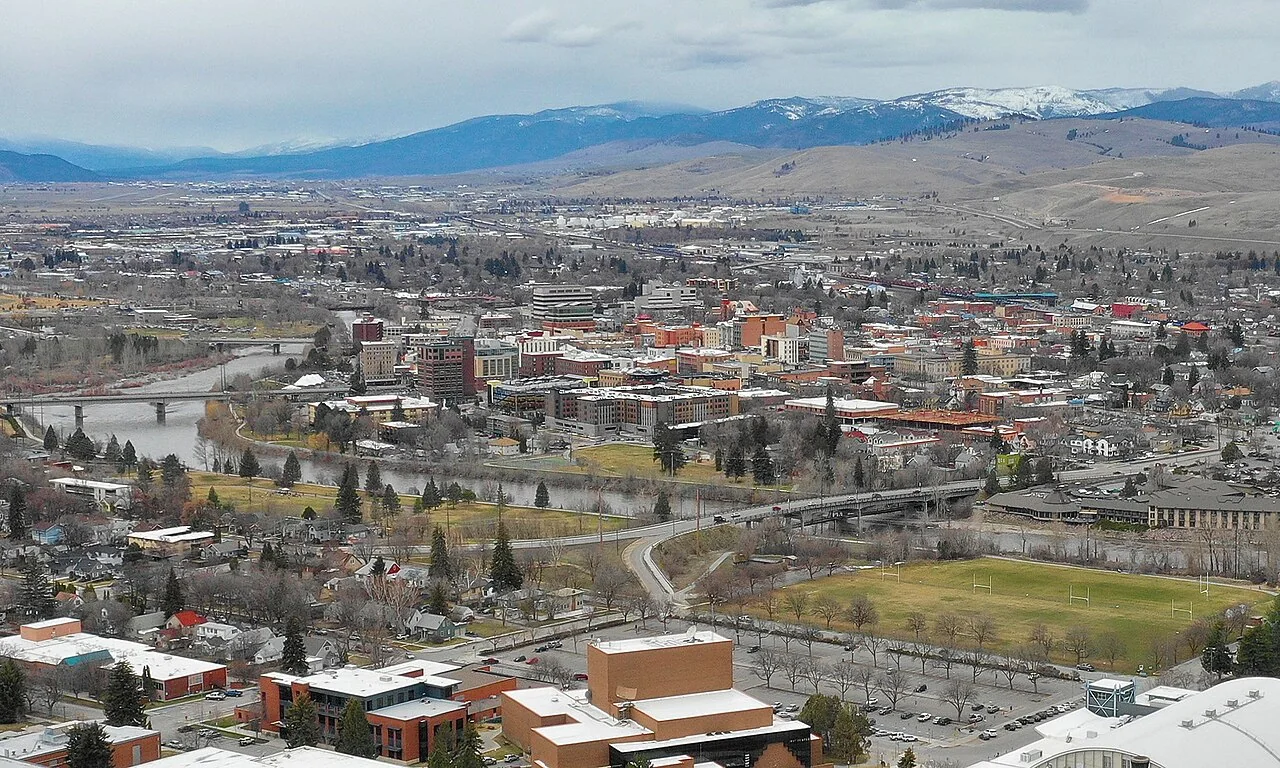

Missoula’s wildfire discussion reaches from developed valley neighborhoods into canyon and foothill communities. A homeowner in Grant Creek may need to explain a wooded setting and approach road, while someone closer to the urban center may need to document roof details, neighboring structures and a smaller yard. An insurance application should make those distinctions visible.
When a renewal notice arrives, it is understandable to feel that the city or neighborhood has been reduced to a label. The most useful response is a factual one: establish what the company is concerned about, identify information that is missing or outdated, and ask a licensed professional which options merit a closer review.
Start with Missoula County’s local assessment
Missoula County’s wildfire-mitigation team advertises free home assessments for county residents. The county explains that the consultation addresses the house and land, with attention beginning at structures and working outward. That is a useful place to turn a vague worry about the surrounding mountains into specific questions about your property.
Bring the insurer’s letter to the discussion, while recognizing that the assessor is not making an insurance offer. Ask for a manageable order of work. A homeowner with limited time or money needs to know what can be maintained immediately, what requires a contractor and what should be coordinated with adjacent owners. Save the recommendations and label their status accurately.
Grant Creek illustrates the value of community detail
The county hosts a 2024 Grant Creek Community Wildfire Protection Plan. Its existence is a reminder that local communities can have planning needs more specific than a countywide overview. For an owner in that area, reading the relevant community document can help identify questions about shared preparation and the home ignition zone.
Do not transfer every Grant Creek observation to the Rattlesnake area, South Hills or another Missoula neighborhood. Instead, describe the setting of the actual house: slope, vegetation, nearby buildings and access. A city guide can point to these distinctions without claiming that it has assigned each neighborhood a risk grade. Public plans are context, not quotations for individual homes.
Use the home ignition zone as a practical work list
The county’s property-preparation guidance discusses roof and yard debris, vegetation close to buildings, vents and material stored around decks. Review those subjects on your own parcel rather than treating distant forest work as the only meaningful action. Ask which changes can be made without creating drainage, structural or other problems.
For a hillside house, photograph the supports and ground beneath outdoor living areas. For a compact lot, look closely at fences, sheds and attachments joining one combustible feature to another. The useful record shows what changed and when. A receipt alone may not show where a product was installed; a photograph alone may not establish what the product is.

Remember that plans change
As checked in September 2026, Missoula County described work on an update to its Community Wildfire Protection Plan. The older county plan and the Grant Creek document therefore need their dates kept with them. Before relying on a recommendation, confirm whether it remains current and whether a newer local project affects your area.
That same habit helps with insurance. An older aerial photograph, a prior inspection and a recently renovated house can tell different stories. Ask the company or agent which information informed the current decision. Provide corrections with evidence and retain the response. A request to correct facts is stronger than an unsupported claim that a whole neighborhood is safe.
Give rebuilding questions enough attention
Missoula owners who have remodeled an older house should explain additions, upgraded finishes and separate structures. Ask how the dwelling estimate reflects the current building rather than its earlier configuration. Montana’s insurance regulator has warned homeowners about underinsurance and explains the importance of replacement cost rather than simply the purchase price or mortgage balance.
Review the proposed limit, deductible and any additional replacement-cost provisions with the licensed professional. Then ask about other structures, contents and additional living expenses. A home office, rental apartment or unusual use belongs in the conversation at the beginning. Clarifying these facts prevents the wildfire discussion from crowding out other important coverage questions.
Prepare for smoke and displacement separately
The county’s wildfire resource pages distinguish property preparation, evacuation and smoke readiness. Follow that distinction in your household planning. Know where official emergency instructions are published, decide how to contact family members and arrange help for anyone who needs it. Keep those plans available outside the home as well as on a phone.
Ask the insurer how your policy addresses smoke damage, evacuation-related expenses and temporary accommodation. Do not equate unpleasant outdoor air or a precautionary trip with an automatically covered claim. If a loss occurs, preserve safe records and follow the company’s reporting instructions. Never delay evacuation to finish an inventory or return for insurance paperwork.
Coordinate across a neighborhood boundary
A Missoula homeowner may control the yard while another owner or agency manages the vegetation beyond it. Bring that boundary into the assessment discussion rather than accepting a recommendation you cannot legally complete. Ask what can be accomplished at the building while the wider question is being resolved.
Where a community plan identifies shared priorities, record who is responsible and what stage the project has reached. A proposed neighborhood effort is useful planning context, but it should not be listed as finished mitigation in an application. Keeping those statuses clear allows an insurance reviewer to understand the present condition without losing sight of future work.
Present the property without overselling it
A concise submission could include the policy notice, a dated photo set, assessment recommendations and a summary of completed work. Add claim and repair information, roof details and the actual occupancy. Be explicit about remaining tasks. An honest description of unfinished work is better than a broad statement that the property has been fully made fireproof.
Our nonrenewal guide helps structure the timeline, and the coverage-options guide supports comparison of proposals. If a policy issue remains unclear, contact Montana’s Commissioner of Securities and Insurance. A careful review can identify the next useful step without promising a particular carrier, premium or outcome.
Explore the Montana guides
Read the Montana wildfire insurance overview for state resources and questions about available insurance paths.
Common questions
Can Missoula County assess my house before I shop for insurance?
The county advertises free wildfire home assessments for residents. Confirm current scheduling and ask for recommendations specific to the home and surrounding property. You can then ask an insurance professional which records are relevant to a submission. The county assessment itself does not bind coverage or guarantee that an insurer will accept it.
Should I use the Grant Creek plan for a home elsewhere in Missoula?
Use it as an example of community planning, not as a substitute for information about another neighborhood. The 2024 document concerns Grant Creek. Confirm the plan and authorities relevant to your own address, and describe the local slope, access and construction without borrowing conclusions from a different area.
What evidence helps when an insurer has old property information?
Identify the precise outdated feature, then supply dated photographs, invoices or inspection records showing the current condition. Ask the agent how to submit a correction and keep the response. A factual update is useful even when it does not change the company’s broader underwriting decision.
Why discuss replacement cost during a wildfire renewal problem?
Obtaining a policy and selecting adequate limits are different decisions. A remodeled Missoula house may cost more to rebuild than an old description suggests. Ask how the estimate was prepared and review its assumptions. The market value, tax value and remaining mortgage do not by themselves answer that question.
Sources and further reading
- Missoula County: prepare your property and home assessments
- Missoula County: 2024 Grant Creek protection plan
- Missoula County: wildfire protection plan update
- Missoula County: wildfire preparation resources
- Montana insurance regulator: underinsurance
Program rules and insurance terms can change. Check the linked agency or program before relying on eligibility, coverage, or local requirements.
General educational information. This website does not issue policies, bind coverage, or provide emergency alerts. Coverage and eligibility require individual review.