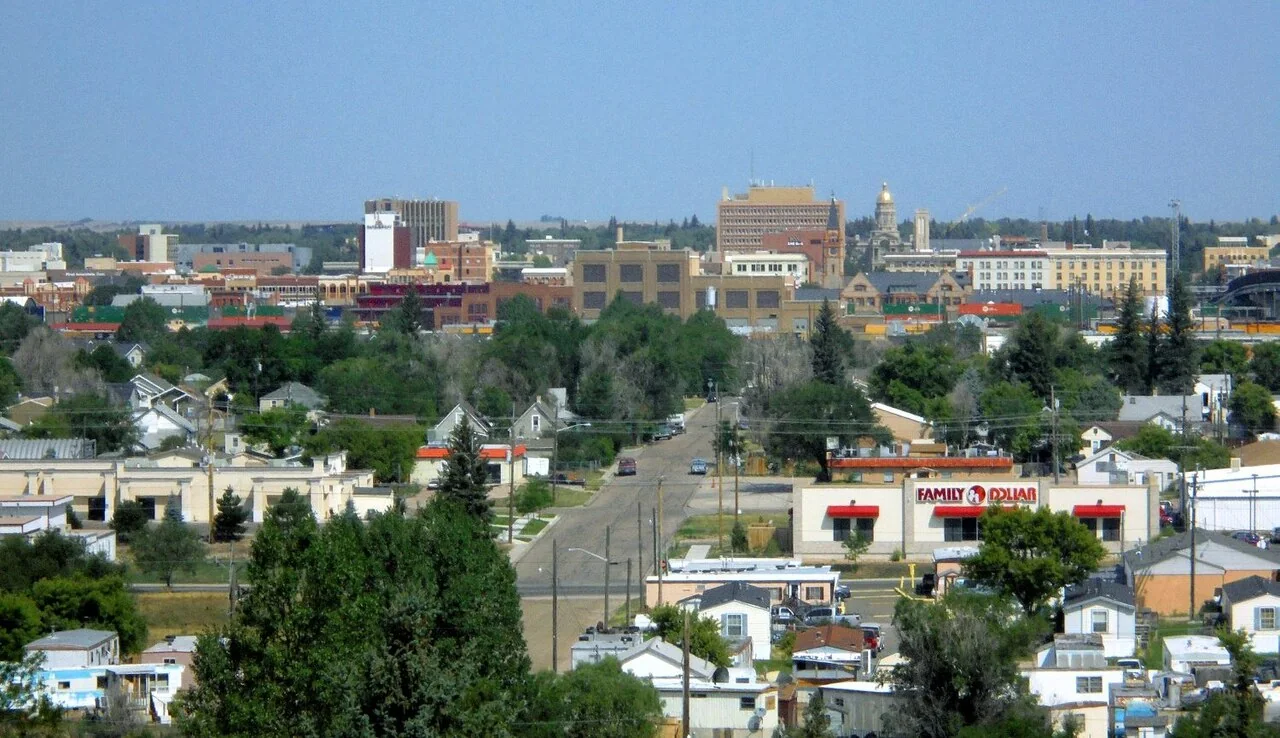

Cheyenne homeowners do not need a dense forest behind the house to have useful wildfire questions. Open grass, brush, stored materials and the edges of developed lots also deserve attention. A city home, an acreage outside the municipal boundary and a property farther toward wooded foothills should each be described on their own terms.
If your insurance application has been declined or your renewal is changing, ask what the company has identified at the property. Then collect evidence relevant to that concern. A licensed specialist can explore possible next steps more effectively with an accurate description than with a broad claim that Cheyenne either has no wildfire issue or is uniformly difficult to insure.
A local vegetation fire offers a modest, useful lesson
In a July 18, 2022 release, Cheyenne Fire Rescue described responding to a vegetation fire on South Greeley Highway. The city reported that grass, brush and trees burned and that a traffic lane was temporarily closed. The account was of a specific past incident, not a forecast for the surrounding neighborhood.
Its practical lesson is that vegetation fire can matter within a developed transportation corridor. Homeowners should look at the fuels and connections on their own lots instead of using the absence of mountain forest as the only measure. The historical incident does not justify assigning a current risk score to every South Greeley property.
Keep Cheyenne and Laramie County roles clear
Cheyenne Fire Rescue provides city fire protection and prevention services. The Laramie County Fire Warden’s page supplies broader county resources, including a fire-district map, district contacts and the Community Wildfire Protection Plan. These resources help owners identify the right authority for an exact address.
Laramie County should also not be confused with the City of Laramie in another county. When searching online or collecting records, check the jurisdiction carefully. An insurance application should use verified service and water information for the parcel, not a nearby place name or the first fire department returned by a search engine.
Inspect the prairie edge of a parcel
For an acreage or subdivision edge, show where maintained ground meets taller or less-managed vegetation. Photograph fence lines, sheds, equipment storage and the approach to the house. On a smaller city lot, focus on the ground around exterior walls and the ways attached features connect. A useful assessment starts with those real conditions.
Ask a local fire professional how to prioritize work under the site’s conditions. Do not undertake mowing, burning or other potentially hazardous activity during restrictions or unsuitable weather. Obtain current guidance from the responsible authority. This insurance guide does not authorize a burn or prescribe a safe time to operate equipment.

Make access visible in the application
A long driveway or shared road deserves its own photographs and explanation. Identify gates, turns and maintenance responsibilities. If an application requests distance or water information, ask how the insurer wants those facts documented and verify them with a reliable local source. Avoid guessing emergency response times.
For households with animals, trailers or members needing assistance, plan ahead with county emergency resources. A road normally used for commuting may have different conditions during an incident. Follow current instructions from authorities and keep important documents available without having to return home. A static article cannot tell you which road is open.
Explain the entire property, including outbuildings
Where a Cheyenne-area home has a workshop, barn or detached garage, list its construction and use. Include business activity, rented space and valuable equipment. Ask which parts belong in the homeowners discussion and which require another coverage arrangement. A building is not fully described by calling it an accessory structure.
Keep a simple inventory and photographs for each significant building. If a roof or exterior has been replaced, retain the invoice and date. Mention any unfinished repairs. These records can improve the accuracy of the submission and help prevent a quote from being based on a building description that no longer matches the property.
Review fire protection alongside wind and roof terms
When wildfire is the immediate concern, it is easy to focus only on whether the company will issue a policy. Ask the licensed professional to examine the entire proposal, including roof settlement and deductibles for different causes of loss. Have the agent explain any differences instead of assuming all damage is subject to one familiar deductible.
Review dwelling limits, separate structures and additional living expenses. Ask how the reconstruction estimate reflects the actual building, additions and finishes. The coverage-options guide can help organize comparisons. A lower premium should be assessed alongside what the contract requires and what financial responsibility remains with you.
Use local preparedness resources before an emergency
The Cheyenne/Laramie County Emergency Management Agency publishes preparedness and response resources, while the Fire Warden links current restriction information and district contacts. Save those official starting points where family members can find them. Recheck active restrictions and instructions rather than relying on a screenshot from an earlier season.
Ask the insurer in advance about smoke, evacuation expenses and reporting a loss. Keep the policy number and claims contact accessible away from the house. Those arrangements reduce confusion, but they do not establish that every disruption is covered. The policy wording, circumstances and required documentation control the claim discussion.
Check the meaning of a restriction notice
County and city notices can concern different jurisdictions or activities. Before handling yard debris at a Cheyenne property, confirm which authority’s rules apply and whether restrictions have changed. A neighbor’s permit or a notice saved last year does not establish permission for your project. Keep routine cleanup planning separate from emergency instructions issued when a fire is already affecting the area.
Respond to nonrenewal with a clear record
Put the written reason and termination date at the front of the file. Add verified district information, current photographs, claim and repair records, and a summary of completed mitigation. If the carrier’s description is wrong, identify the exact discrepancy and provide evidence. Our nonrenewal guide helps keep the timetable visible.
The Wyoming Department of Insurance offers consumer resources for policy and claim questions. Use that support when needed while a licensed specialist evaluates possibilities. A difficult renewal deserves careful attention, but the next step should be driven by property facts and actual proposals rather than assumptions about all prairie or city homes.
Explore the Wyoming guides
Read the Wyoming wildfire insurance overview for state resources and questions about available insurance paths.
Common questions
Can grass and brush matter even when my Cheyenne home is far from forest?
Yes. Examine the vegetation and connected features at the property rather than judging the setting only by large trees. Ask a qualified local professional about the house and surrounding ground. The documented South Greeley incident is historical context, not a prediction or a risk rating for your address.
Where can I verify my Laramie County fire district?
Start with the county Fire Warden’s official page, which links district mapping and contact information. Confirm the parcel details with the responsible authority before using them in an application. A Cheyenne mailing address or the nearest station on a navigation map is not enough to establish service arrangements.
Should I treat Laramie County and the City of Laramie as the same jurisdiction?
No. Check that the resource concerns Cheyenne and Laramie County when that is where your home is located. Similar place names can produce irrelevant search results. Accurate jurisdiction information matters for planning, local contacts and the property facts submitted to an insurer.
What should I compare if one Cheyenne quote is much cheaper?
Ask the agent to explain the dwelling estimate, roof settlement, all applicable deductibles, separate structures and additional living expenses. Review inspection conditions and required repairs too. Compare the assumptions and policy wording so the lower price is not evaluated without understanding the proposed protection.
Sources and further reading
- City of Cheyenne: July 2022 South Greeley vegetation fire
- City of Cheyenne: Fire Rescue
- Laramie County: Fire Warden and district resources
- Laramie County: emergency management
- Wyoming Department of Insurance: consumer guides
Program rules and insurance terms can change. Check the linked agency or program before relying on eligibility, coverage, or local requirements.
General educational information. This website does not issue policies, bind coverage, or provide emergency alerts. Coverage and eligibility require individual review.