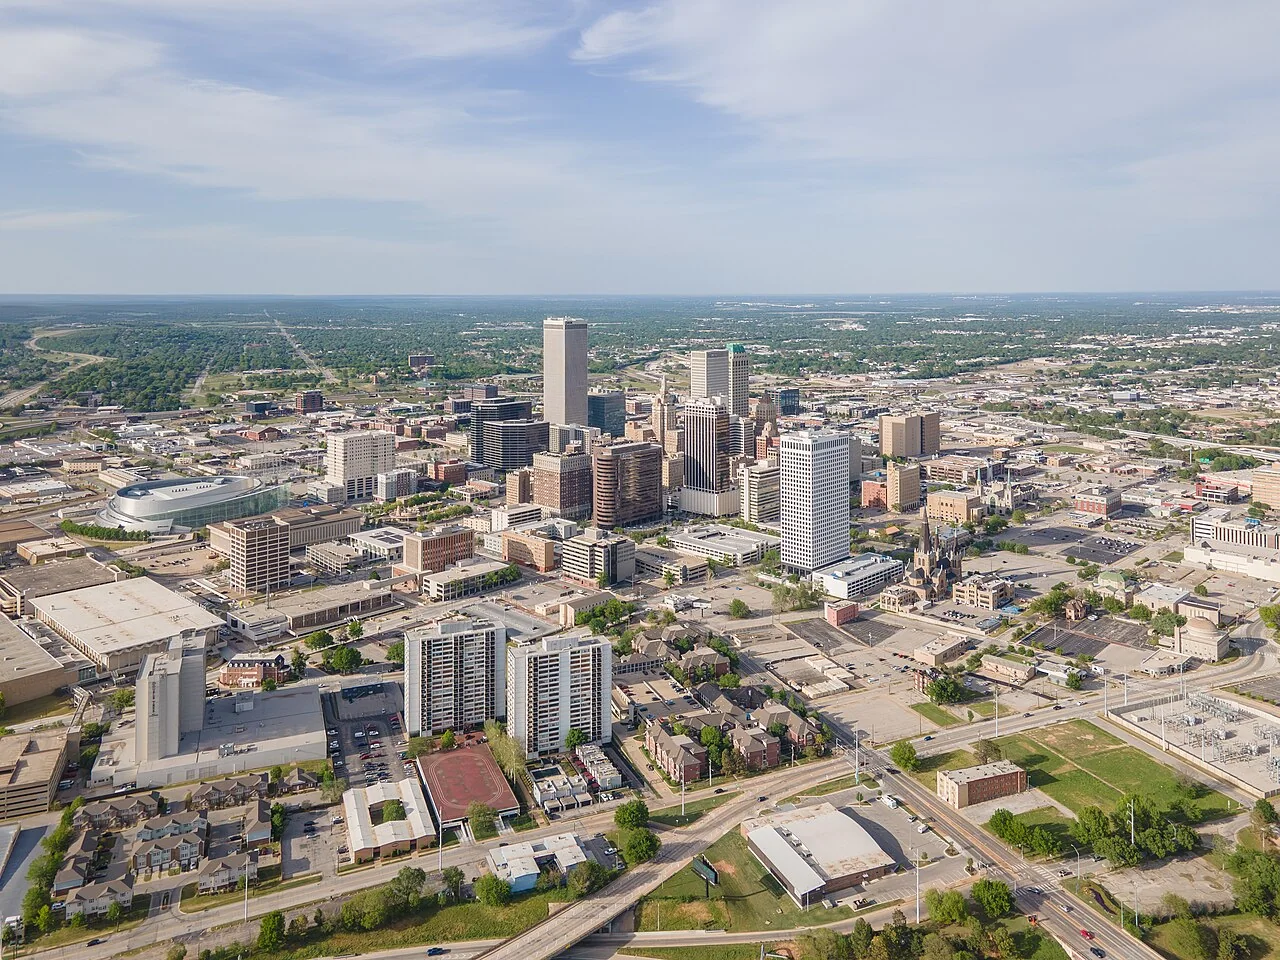

Tulsa has landscapes that can surprise someone expecting Oklahoma to be only open grassland. Turkey Mountain's wooded terrain, the Arkansas River corridor and natural areas associated with Oxley Nature Center illustrate that variety. None of those places provides a shortcut to deciding whether a particular Tulsa house will qualify for insurance.
For a homeowner dealing with a wildfire-related concern, the useful work is more specific: describe the building, show the vegetation and structures around it, confirm completed repairs and clarify the coverage deadline. A licensed specialist can then evaluate available options using a property record rather than a broad claim about the city.
Turkey Mountain demonstrates the importance of managed urban woodland
River Parks Authority's Turkey Mountain information describes a substantial public recreation landscape within the Tulsa area. Its planning and published updates address management of vegetation. State forestry records also document agency involvement in prescribed-fire work there. This is active land management, not simply unused space on a map.
A neighboring property owner should ask where the public boundary lies and who manages it before proposing any work. Public woodland treatment does not remove the need to maintain a private roof, fence or deck, and it should not be represented as a guarantee about future fire behavior. For an insurance submission, separate work completed on your lot from projects administered by the park authority.
A photograph of Turkey Mountain can explain Tulsa's landscape, but it cannot describe the back of your house. Supply closer images showing the relationship between the building, slope, garden and adjacent land. If the insurer asks for measurements or a technical inspection, obtain those through a qualified source instead of estimating from a regional photograph.
Oxley and Redbud Valley illustrate another side of Tulsa
Oxley Nature Center is part of the city's parks system, and its information about Redbud Valley explains a conservation setting with distinctive plant communities. Their relevance here is geographical and ecological. They are not a list of neighborhoods to avoid and do not assign an insurance classification to surrounding residences.
Where a private lot meets a drainage or natural area, show the edge clearly. Identify leaf accumulation, storage near fencing and any structure extending into a wooded portion of the lot. If the home is instead within a more closely built neighborhood, document nearby buildings and connecting fences. The appropriate description changes with the property rather than with a single citywide label.
Discuss the whole building, including what the street view misses
An attractive front elevation can hide an older porch, an open under-deck area or a detached garage. Include those elements in your maintenance and insurance review. Show the roof installation date when it is known, and retain specifications for major upgrades. Avoid assuming that masonry on the front tells the reviewer how every wall or attachment is constructed.
For older Tulsa residences, ask how additions and remodeling have been recorded. A current room layout, finished area or detached structure may differ from earlier records. If a discrepancy appears, address it with supporting documents. The goal is not to persuade an insurer through adjectives; it is to make the physical description accurate enough to evaluate.

Turn storm-repair paperwork into a clear chronology
If the property has prior wind, hail or water claims, keep the dates and repair records organized alongside the wildfire material. Explain each event separately. A roof invoice from one claim and landscaping work performed later answer different questions, even though both may be relevant to the current state of the property.
When you receive an inspection request, ask which items are missing and how they should be submitted securely. Use dated images that match the present building. If a claim is still open or repairs remain incomplete, state that directly. An agent can help with an accurate account; an application should not suggest completed work where only a contractor estimate exists.
Consider how ownership and occupancy shape the quotation
Tulsa properties may be owner-occupied, rented to others or divided into separate living spaces. Describe the actual arrangement at the start. If you own a rental house near a wooded edge, do not assume the occupants' personal belongings are treated like the owner's building. If you occupy a condominium, ask which responsibilities belong to the association and which belong to you.
For a detached office or workshop, disclose the activity and contents. Ask the agent to identify any gap between how the building is used and how it is described in the proposed contract. Wildfire concerns are only one part of an accurate submission; the policy must also fit the people and activities at the address.
Ask specific questions about recovery after a covered loss
Review the dwelling reconstruction estimate, other-structure limits, personal property terms and applicable deductibles. Ask how smoke damage and debris removal are addressed. If covered damage would displace the household, request the details of any temporary living expense benefit, including its conditions and limits. These questions reveal more than comparing premiums alone.
The Oklahoma Insurance Department's wildfire information emphasizes keeping records and documenting losses. Build that inventory before an emergency, with photographs and descriptions stored somewhere you can access away from the house. Include items in a detached garage or studio that might otherwise be forgotten during a hurried claim preparation.
If a company declines or nonrenews the property, a licensed agent can review other available markets. Ask for the reason in writing and identify whether wildfire, repairs, loss history or another factor is involved. Our insurance-options guide can help you compare the terms of proposed alternatives without assuming a certain insurer or price is available.
Use Tulsa emergency resources for immediate decisions
The City of Tulsa Department of Emergency Management coordinates local preparedness and response functions. Use its official information and other responsible agencies for current instructions. A map of a public park or a saved image of a past burn is not a live incident map.
Plan how household members will communicate when they are in different parts of the city. Keep pets, medication and assistance needs in that plan. Avoid assuming a river crossing or commuting route will always be available during an incident. If officials direct an evacuation, follow their directions rather than waiting for an insurer to answer a coverage question.
There is room for a practical, reassuring approach: improve the information, complete appropriate maintenance and request an informed coverage review. Tulsa's diverse landscape makes specificity valuable. It does not justify treating every homeowner near green space as the same risk.
Explore the Oklahoma guides
Read the Oklahoma wildfire insurance overview for state resources and questions about available insurance paths.
Common questions
Does Turkey Mountain’s vegetation management guarantee nearby coverage?
No. Public land management and insurance eligibility are separate matters. Describe any work on your property accurately and identify park projects as outside your control. Ask the agent what evidence the insurer will consider for your specific home.
Can I clear a natural-area boundary behind my Tulsa house?
Confirm ownership and obtain authorization before entering or altering land beyond your property. Contact the relevant land manager about shared concerns. Focus your own maintenance record on lawful work around the building, fences, decks and storage areas.
Why mention a detached studio in a wildfire insurance conversation?
Its construction, contents and use may affect the coverage you need. Tell the agent if it contains business equipment or is rented. A quotation based only on the main residence can leave those details insufficiently explained.
What if my home is nowhere near Turkey Mountain or Oxley?
Use the discussion as a method, not a claim about your location. Document the actual adjoining lots, vegetation and buildings. Tulsa’s named natural areas demonstrate local variety; they do not define the exposure of every address in the city.
Sources and further reading
- River Parks Authority: Turkey Mountain
- River Parks Authority: Management accomplishments
- Oxley Nature Center
- Oxley Nature Center: Redbud Valley
- City of Tulsa: Emergency Management
- Oklahoma Department of Agriculture: June 2023 board materials
- Oklahoma Insurance Department: Wildfires
Program rules and insurance terms can change. Check the linked agency or program before relying on eligibility, coverage, or local requirements.
General educational information. This website does not issue policies, bind coverage, or provide emergency alerts. Coverage and eligibility require individual review.